

The Bike Rack Question, Answered
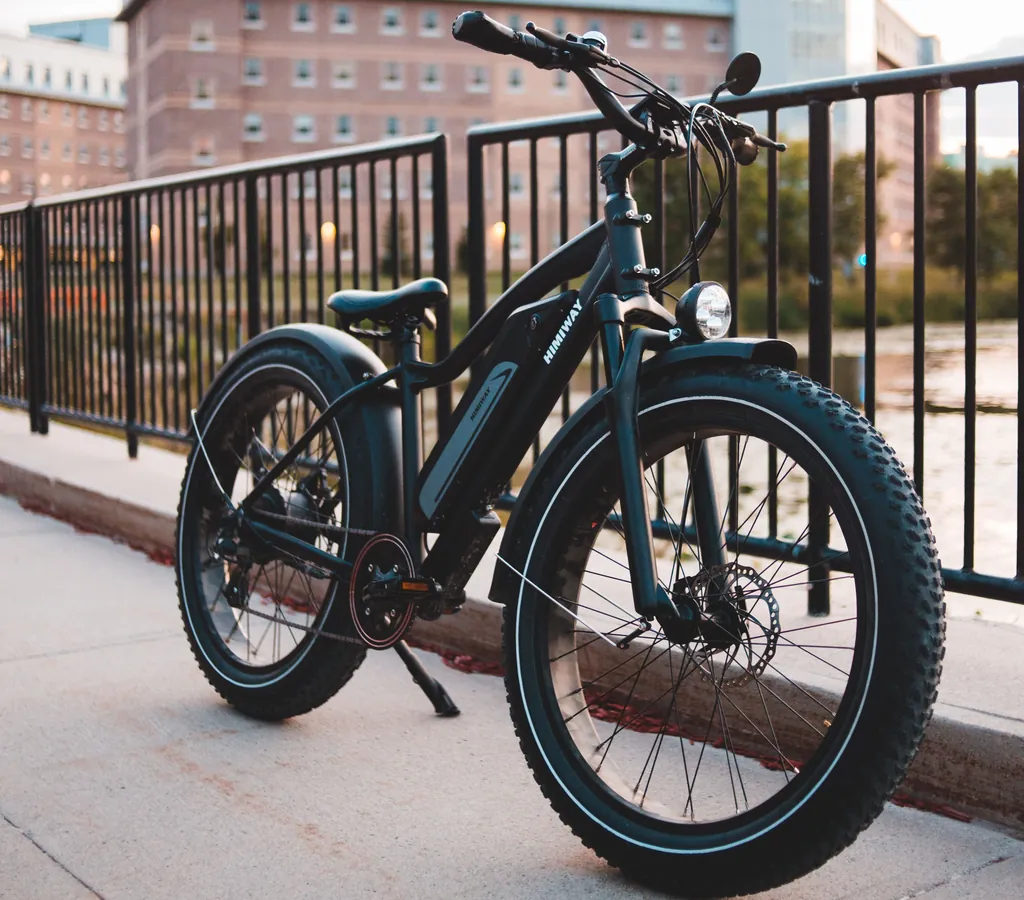
E-bikes are more popular than ever, and for many urban commuters they have replaced the car. Most of them spend the day locked outside an office, a school, or a station, and that is where they become theft targets: popular, valuable, and easy to resell. A 2025 survey by UC Davis, UC Santa Barbara, Bike Index, and YouGov put US bike theft at 2.4 million bikes a year, worth $1.4 billion, with 13% taken from an outdoor bike rack. Fewer than 5% of stolen bikes are ever recovered. Theft is part of the core Velosurance policy. Pick a card to jump to the details.
Locked to the Rack
Lock the e-bike to the rack with a key or combination lock and a theft is a covered loss, even if the thief defeated the lock.
Which Racks Count
A bike rack anchored in the ground is an immovable object. A rack a thief can unbolt, or a post the lock lifts over, is not.
What the Claim Pays
The value you insured the e-bike for, minus your deductible, with no depreciation for age.
The Short Answer: Yes, If It Was Locked
Theft is part of the core policy, and the bike rack is the case it was written for.

You locked your e-bike to the rack outside the office, the gym, or the train station and came back to a cut lock and an empty slot. Under a Velosurance policy, that is a covered theft. The policy's condition for an unattended bike away from home is that it was locked to an immovable object with an appropriate security device, and a bike rack with a key or combination lock through the frame is exactly that.
How the thief got through does not change the answer. An angle grinder through a U-lock, bolt cutters through a chain, a pried shackle: each is a covered theft, and the defeated lock is the evidence that the bike was secured. Fault is not part of the claim. You did what the policy asked, and the claim pays the value you insured the e-bike for, minus your deductible, with no depreciation for age.
Theft coverage is part of the Velosurance core policy, not an add-on. The policy is all-risk, meaning anything not specifically excluded is covered: theft (subject to the policy's locking conditions), crash and accidental damage, and loss or damage in transit by car, airline, or courier. It is a standalone policy, from $9 a month, with no renters or homeowners policy required behind it. Theft at home, away from home, and from a car is covered in full on our bicycle theft insurance page.
Locked to the Rack
The lock is the whole case. Here is what the policy asks of it.

A key or combination lock, fastened to the rack. An appropriate security device is a key or combination lock built to fasten a bike to a bicycle stand or an immovable object. The policy sets no brand or price requirement. We recommend a quality U-lock or a sleeved chain and would skip the cable: a cable lock will not save your bike from theft.
Through the frame. Put the lock through the frame and the rack, not around a wheel alone. A quick-release front wheel left locked to the rack while the rest of the e-bike rides away is a conversation you do not want to have with a claims manager. A second lock through the rear wheel and frame closes the gap.
A frame lock on its own is not enough. The ring lock built into many commuter e-bikes immobilizes the rear wheel but fastens the bike to nothing. Away from home it does not meet the locking conditions by itself. Use it as the second lock, with a U-lock or chain to the rack as the first.
Keep the cut lock. Whatever is left of the lock after the theft is your proof that the bike was secured and that force was used. Photograph it where it lies, then take it with you. Our picks are in the lock we recommend.
Which Racks Count
An immovable object is anything a thief cannot undo, lift the lock over, or carry off with the bike.

The rack outside the office qualifies. So does the one at the train station, the grocery store, the campus, the library, and the trailhead. The policy's definition of an immovable object is a bike rack or a solid object fixed in concrete or stone that a thief cannot undo, remove, or lift the lock clear of. A properly fixed roof rack or bike rack on your car counts as well.
Any hour, any length of stay. Coverage applies anywhere in the US and Canada, overnight as well as during the workday, with no limit on how long the e-bike is left locked away from home. A 10-hour shift and a weekend at the station are covered the same way, as long as the lock is on.
Look at what the rack is bolted to. A wave rack sitting loose on the pavement, a sign post short enough to lift the lock over, and a fence panel that unbolts are not immovable objects. If the rack moves when you push it, lock to something else.
Shared bike rooms. A shared bike room creates a false sense of security. With dozens of residents, building staff, and guests holding keys or fobs, the "secured" room is far more accessible than it feels. Lock your bike inside the room exactly as you would if you were leaving it unattended on the street: to the provided rack, a solid pipe, or if the room is a cage, to the cage itself.
Why E-bikes are the Target
The most valuable thing on the rack, with parts that resell on their own.

Bike Index logged a 15% rise in reported thefts in 2024. The reasons are not mysterious: an e-bike is usually the most expensive bike on the rack, its battery and motor sell quickly on their own, and a cordless angle grinder gets through most locks. What puts a bike on a thief's list, and how to keep yours off it, is in how to make sure that your bike remains yours.
Same policy, same rules. Velosurance insures Class 1, Class 2, and Class 3 e-bikes with a maximum assisted speed of 28 mph, under the same theft conditions as a conventional bike and at the same price for the same insured value. High-power electric dirt bikes are not covered. The details are on our e-bike insurance page.
Take the battery with you. The battery is the part a thief wants most, and on most e-bikes it is the one part that comes off and goes into the office with you. Without it the e-bike is a slower, heavier target. Insure the e-bike for its full price with the battery, and declare the accessories you add later so they are part of the insured value.
Make the bike traceable. Photograph the e-bike from both sides, including a clear shot of the serial number, register it with Bike Index, and keep a copy of the purchase receipt on file. Fewer than 5% of stolen bikes are recovered; photos and a serial number give the police something to work with, and the receipt backs up the claim. The patterns thieves follow are in how bicycle theft happens.
What Is Not Covered
The exclusions are written into the policy, so you know where coverage stops before you lock up.
An unlocked e-bike. Away from home, an unattended bike left unlocked, even for the minute it takes to grab a coffee, is not covered for theft. Lock it every time, even outside the window you are watching from.
A lock on something movable. A rack that is not anchored, a post the lock lifts over, or a fence panel that unbolts is not an immovable object, and a theft from one does not meet the locking conditions.
A frame lock alone. A built-in ring lock immobilizes the wheel but does not fasten the e-bike to anything. On its own it does not satisfy the away-from-home condition.
Theft by someone you trusted. Theft by a person you entrusted the e-bike to is excluded. Lending is fine under permissive use; the exclusion is for the borrower who never brings it back.
Commercial use. Delivery and courier work is commercial use, which suspends coverage for as long as the e-bike is used that way. An e-bike stolen from the rack outside a restaurant mid-shift is not a covered theft.
An abandoned bike, and a missing police report. Abandonment is excluded, so a dead battery is a reason to push the bike home, not to leave it overnight unlocked. And every theft claim needs a police report detailing the time, place, and manner of the theft and the lock that was used. File it the same day.
What the Claim Pays
Stated value with no depreciation. The number you insured is the number the claim starts from.
A stolen e-bike is a total loss. The claim pays the value you insured the e-bike for, minus your deductible. Age does not shrink the payout: an e-bike insured for $2,500 pays $2,300 after a $200 deductible, whether it is three months old or three years old.
Insure what you spent. Stated value includes the battery and the accessories and upgrades you declare, so add the rear rack, the lights, or the second battery to the policy when you buy them. See how to value your bicycle.
Gear and spare parts. Spare parts are covered for theft under the same locking conditions, up to $500 per loss with a $1,000 policy term limit. Cycling apparel lost in the same covered theft has its own $500 per loss and $1,000 policy term limit.
How the claim is handled. Once you file a claim, a claims manager contacts you within two business days, and most claims are paid in under 14 business days. Any remaining installments on the annual premium are due before the payout is issued. After a total loss payout on a single-bike policy, the policy closes automatically, since the bike it covered is gone. On a multi-bike policy, the lost bike is removed and coverage continues for the rest. Either way, when you buy a replacement e-bike, insure it the day you bring it home.
Renters and Homeowners Policies at the Rack
Most riders find out what their home policy covers after the e-bike is gone.

The motor is the problem. Renters and homeowners policies routinely exclude anything with a motor, and an e-bike has one. Read the motorized vehicle exclusion in your policy before you count on it for a theft from a bike rack. The homeowner's version of the problem is on the homeowners insurance e-bike exclusion page.
Then the math. Where a home policy does respond, many pay actual cash value, the e-bike's depreciated worth, after a deductible that often runs $500-$2,000, and some cap property away from home. A three-year-old e-bike can come back as a check well short of a replacement, and the claim goes on your home insurance record.
A standalone policy keeps it separate. Velosurance needs no renters or homeowners policy behind it, pays the value you insured the e-bike for, and keeps the claim off your home record. The side-by-side numbers are in Velosurance vs. renters insurance and Velosurance vs. homeowners insurance.
What to Do If Your E-bike Is Taken From the Rack
Every theft claim runs on one document: the police report.
1. File a police report the same day. Every theft claim requires one. The report needs the time, the place, how the theft happened, and the lock you used. Get the case number.
2. Photograph the scene and keep the lock. Shoot the rack, the empty slot, and whatever is left of the lock before you move it, then take the lock with you.
3. Ask about cameras. Offices, stations, and storefronts often have a camera pointed at the rack. Ask the same day, before the footage is overwritten, and give the case number to whoever holds it.
4. Start the claim. Follow the steps on our claims page and include the police report, the photos, your receipts, and a written account of the theft. A claims manager contacts you within two business days.
Do the paperwork before you need it. Record the serial number, photograph both sides of the e-bike and the battery, keep your receipts, and register the bike. A complete file speeds up both the police report and the claim.
We cover all types of bikes
Whether you ride the tarmac or shred the gnar, dodge pedestrians, or cruise the beach, you're a member of a special club of people who appreciate the world in a primal way – on two wheels. To keep you rolling, we address the specific risks associated with your discipline.
Road bikes
Light and aerodynamic, equipped with skinny tires and optimized for long days in the saddle.
E-bikes
Electrically-assisted Class 1, 2, and 3 e-bikes with maximum assisted speed of up to 28 mph.
Commuter bikes
Simple, reliable bikes designed specifically for urban environments.
Mountain bikes
Rugged, resilient, and incredibly fun. Equipped with suspension and designed to offroad, tackle technical terrain and jumps.
Gravel bikes
Drop bar bikes capable of going on both pavement and unprepared terrain, even mild singletrack.
Triathlon bikes
Exceptionally aerodynamic and lightweight, these speed machines are designed with one goal in mind: go fast.
Trikes
Three-wheeled bicycles are known for additional stability and versatility.
Recumbent bikes
Two and three wheeled bikes with a leisurely leaning back seating position.
Cargo bikes
The SUVs of the two-wheeled world, these bikes are designed to carry heavy loads, including groceries and passengers.
Coverages and Features
Velosurance offers must-have protection such as accidental damage, theft, or loss in transit. Each policy can be customized by adding additional coverages such as liability protection, uninsured motorist, and medical payments.
Bicycles are very easy to steal and equally difficult to recover, and even a hefty U-lock doesn’t guarantee your bike is still there when you return. Velosurance provides peace of mind if it is stolen or damaged in the process.
Bike theft insurance →Our policy will pay to replace your ride if it is accidentally damaged and beyond repair, including damage that occurs while being carried on or in your vehicle. If it can be repaired, we will pay all the costs associated with the bike's repair, including tax, labor, and shipping, minus the deductible. Cosmetic damage that does not affect safety is excluded.
Bicycle crash insurance →Our policy optional coverage purchase will protect and defend you from your personal liability (injury, sickness, death, or damage to property, including fire damage) that you are found legally liable for. Coverage limits offered: $25,000, $50,000, $100,000, $300,000 or $500,000 per occurrence.
E-bike liability insurance →If you’re hurt and require medical attention, our optional medical gap will take care of your medical bills, up to the selected limit. The payments are paid directly to you to supplement the deductible of your personal health insurance policy.
Medical gap insurance →Depreciation is a hidden deductible that increases every year and is applied if the bicycle is stolen or totaled. No one is ever happy with an Actual Cash Value insurance settlement: the bike is first devalued, and then a deductible is applied, resulting in a reimbursement that is far less than the cost of a replacement. We reimburse without depreciation, for the cost of a replacement that is of like, kind, and quality similar to your totaled bike.
One of the scariest things that can happen to a cyclist is getting hit by a car. This coverage will pay for medical expenses, physical therapy, mental health services, lost wages, and other expenses that arise from a bicycle-car accident.
Uninsured motorist insurance →We cover all electrically assisted Class 1, 2, and 3 bikes with a maximum assisted speed of 28 mph. All protections available for conventional bicycles also apply to electric ones.
E-bike insurance →Bikes often get damaged in transit by personal vehicles, airlines, or courier services. Filing a claim with the airlines and courier services is a notoriously difficult process with a questionable outcome. We cover the insured bicycle for loss or damage while it's on its way to or from your destination by air or road. Even if it falls off a vehicle rack or is hit in a rear-end accident, it is covered, no arguments.
Bicycle travel coverage →If you go down in a crash, we cover your ride as well as your apparel, such as helmet, shoes, glasses, or riding kit that are torn up, and pay up to $500 per accident and $1,000 per term. Spare parts that are not installed, such as a spare wheelset, are also covered up to $500 per loss and $1,000 per year.
Our policy does not piggypack on any coverage you may already have, such as homeowners policies. Filing a claim won’t impact your rates with other carriers. With home insurance premiums rising each year in the U.S., it’s wise to reserve that policy for major incidents, because no matter how valuable your bike is, it’s still a lot cheaper than a kitchen fire or a flooded basement.
We cover the insured bike at all times, anywhere in the USA and Canada, and can be extended worldwide on request. There are no exclusions on the time of day or limitations on how long it can be stored away from home. 24/7/365 means every minute of every day, no matter where or when.
In the heat of a race, the focus on speed often outweighs concerns for safety, leaving little margin for error. If you go down in a crash, this optional coverage takes care of repairs or replacement. If you use your bike in a competitive environment, this is a no-brainer because it offers protection in the highest-risk category.
Bicycle racing insurance →If your travels take you beyond the USA and Canada, for a small additional premium, this option extends the physical loss and damage protection, including loss or damage caused by an airline, to any country in the world.
International coverage →You can lend it to anyone you choose, and it will be covered. The bike and the person riding it are covered as if it were you riding it‚ this includes theft and crash damage as well as any purchased optional coverages.
We do not dictate what type or brand of lock must be used to protect your ride from theft – you are welcome to use any lock that you trust. The best security is provided by metal locks combined with a high-quality chain. Securing your ride to a solid and immovable object, such as a bike rack, with a high-quality lock will send the thief onto the one secured with a more vulnerable lock.
Why Velosurance is a Better Policy for E-bikes Locked Outside
Renters and homeowners policies routinely exclude anything with a motor, pay a depreciated value after a larger deductible when they do respond, and put the claim on your home insurance record. A standalone e-bike policy keeps the claim and the payout separate.
| Policy Coverage |  | Homeowner/Renters Policy |
|---|---|---|
| Insured at Full Value | Yes | Possibly |
| Crash Damage | Yes | No |
| Theft Coverage | Yes | Limited |
| Theft by Force | Yes | No |
| Theft of Accessories | Yes | Limited |
| Theft Away From Home | Yes | Possibly |
| Uninsured Motorist | Yes | No |
| Personal Liability | Yes | Possibly |
| Permissive Use Policy | Yes | No |
| Replacement Rental | Yes | No |
| Event Fee Return | Yes | No |
| Cycling Apparel Coverage | Yes | No |
| Medical Payments | Yes | Possibly |
| Racing Coverage | Yes | No |
| E-bikes | Yes | No |
| Coverage in-transit | Yes | No |
| USAC, USAT and IMBA Member Discount | Yes | No |
| FREE INSTANT QUOTE |
Not all insurance policies provide the same level of protection, and many people only discover gaps in their coverage after filing a claim. We’ve done the hard work of reviewing the fine print. To see how plans compare, check out our insurance comparison.
Client satisfaction is our #1 goal, and we strive to deliver the best experience every time. Here's what our clients say about Velosurance:


Velosurance really stepped up and put me at ease. The claim was fast and easy. I am insuring all my bikes now.

Check out Velosurance reviews to see what people are saying about us.
Frequently Asked Questions
- Does insurance cover an e-bike stolen from a bike rack?
- Yes, when the e-bike was locked to the rack with an appropriate security device, meaning a key or combination lock. Theft is part of the core Velosurance policy, and the claim pays the value you insured the e-bike for, with no depreciation, minus your deductible. File a police report the same day.
- What lock do I need for theft coverage at a bike rack?
- Any key or combination lock designed to fasten a bike to a fixed object qualifies as an appropriate security device, and the policy sets no brand or price requirement. We recommend a quality U-lock or a sleeved chain, since cable locks are easily defeated. Put the lock through the frame, and keep whatever is left of it after a theft.
- Is the e-bike covered if the thief cut through my U-lock with an angle grinder?
- Yes. How the lock was defeated does not change the claim: a ground-through U-lock, a cut chain, or a pried shackle is a covered theft, and the broken lock is the proof that the bike was secured. Photograph the lock where it lies, keep it, and describe it in the police report.
- Which bike racks count as an immovable object?
- A bike rack anchored in the ground counts, and so does any solid object fixed in concrete or stone that a thief cannot undo, remove, or lift the lock clear of. The racks outside offices, stations, stores, and campuses all qualify. One thing to watch: a loose rack or a short post the lock lifts over does not.
- Is my e-bike covered if it stays locked at the train station overnight?
- Yes. Coverage applies anywhere in the US and Canada at any hour, with no limit on how long the e-bike is left locked away from home, as long as it is locked to an immovable object with an appropriate security device. Add worldwide coverage to the policy before a trip abroad.
- Does theft coverage apply to Class 1, Class 2, and Class 3 e-bikes?
- Yes. Class 1 (pedal assist to 20 mph), Class 2 (throttle to 20 mph), and Class 3 (pedal assist to 28 mph) e-bikes are covered for theft under the same locking conditions as a conventional bike, at stated value with no depreciation. High-power electric dirt bikes are not covered.
- Is an e-bike in my apartment building's bike room covered?
- Lock the e-bike to the rack inside the room with a key or combination lock and keep the room's door locked behind you; that puts the strongest facts on your side. One thing to settle first: whether a shared bike room is treated as home or away from home for the locking conditions, so ask us about your building before you rely on it.
- How much does a stolen e-bike claim pay?
- The claim pays the value you insured the e-bike for, minus your deductible. The bike is insured at stated value with no depreciation, so an e-bike insured for $2,500 with a $200 deductible pays $2,300 at any age. One thing to watch: paying a total loss ends the policy, so insure the replacement e-bike the day you buy it.
- Can I rely on the frame lock built into my e-bike?
- Use the frame lock as your second lock. It immobilizes the rear wheel but does not fasten the e-bike to anything, so on its own it does not meet the away-from-home condition; a U-lock or sleeved chain through the frame to the rack does. Together, the two locks make the e-bike a slower target.
- What do I need to file the claim?
- A police report, filed the same day, is the document every theft claim requires. Add photos of the rack and the defeated lock, receipts for the e-bike and any gear claimed, and your written account of the theft, then start the claim on our claims page. A claims manager contacts you within two business days.
Insure the e-bike before the next lock-up
Theft coverage cannot be added after the e-bike is gone. Insure it today, from $9 a month, and the next time you lock it to a rack the payout is already settled.